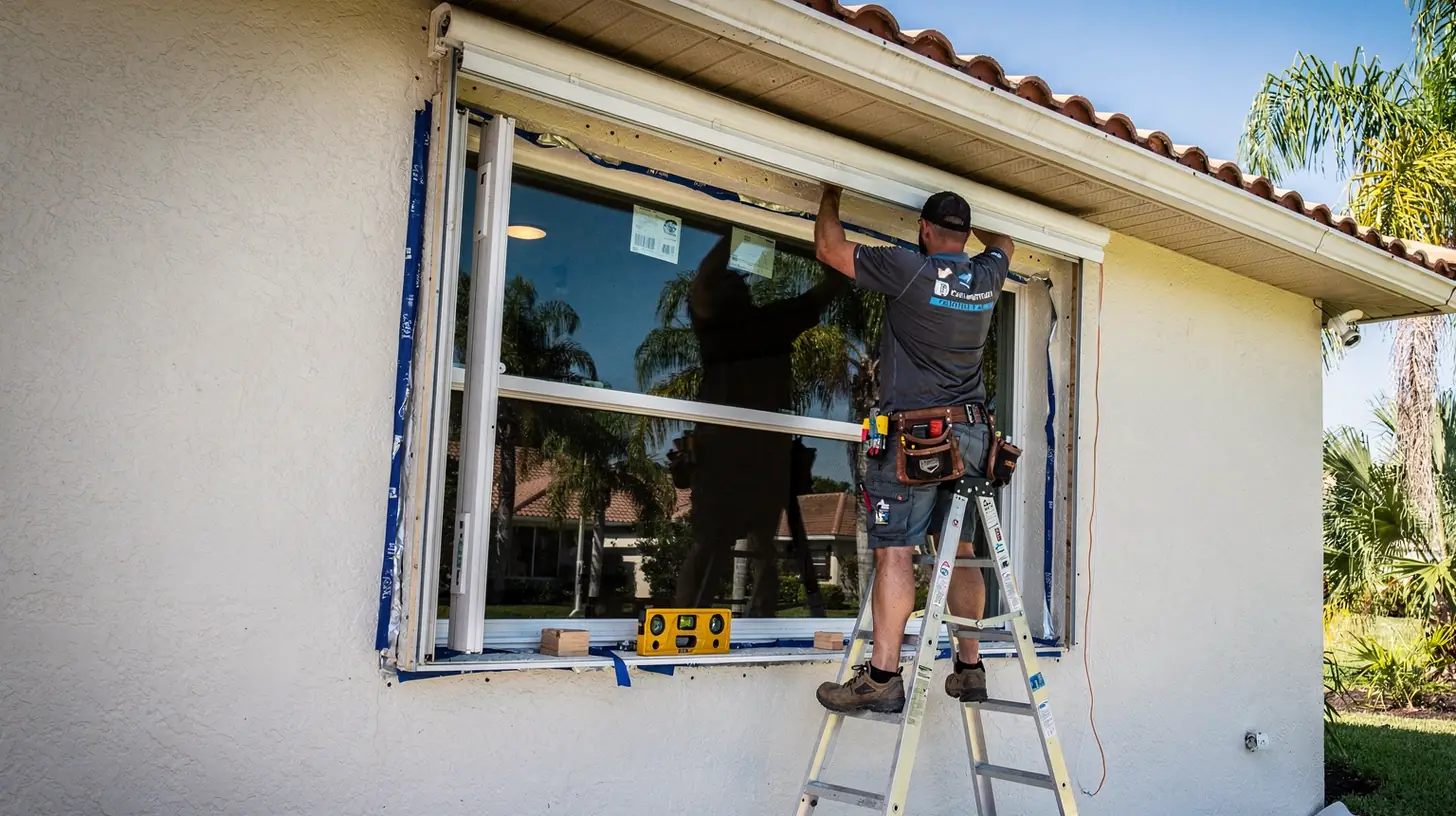
The Three Questions Impact Window Buyers Ask Before They Call Anyone
A homeowner deciding whether to spend thirty or eighty thousand dollars on impact windows does not begin by looking for an installer. They begin by trying to work out whether it is worth it, and that question breaks into three: will this satisfy the code, will my insurance actually come down, and how do I know the product is what the salesman says it is. Two of those have documented answers that are public and checkable. Almost no installer website in Collier or Lee County answers any of them.
The install is the last two days of a decision that took the homeowner four months. Almost all of the marketing is aimed at the two days.
In one paragraph
Impact window and shutter SEO means ranking for the code, insurance and product verification questions homeowners research during a long, high-value buying cycle, rather than competing only for the install query that happens at the very end of it.
01 / 06
The Calendar Decides the Search, and You Are Inside It Now
NOAA puts the Atlantic hurricane season at June 1 to November 30, with the peak on September 10 and most activity between mid-August and mid-October (NOAA National Hurricane Center, 2026). Demand for openings work is driven by that curve, and the content that captures it has to exist before the curve arrives, not during it.
Start with the shape of the year, because in this trade it dominates everything.
The Atlantic hurricane season runs from June 1 to November 30, the peak falls on September 10, and most activity occurs between mid-August and mid-October (NOAA National Hurricane Center, 2026). Nothing about that is a surprise to anyone who lives here, and yet it is treated as a surprise by most marketing in the category.
The consequence is specific. A page published in September, when a storm is in the forecast cone, has not had time to be found, crawled and trusted before the moment it was written for. Search is not a switch. The page that earns the September buyer is one that has been sitting there since spring, quietly accumulating the signals that let it rank.
So the practical planning rule for this trade is to write for the peak six months before it and to keep the pages alive year round. That also matters because the genuinely valuable buyer is not the one panic-buying plywood in a warning cone. It is the homeowner in February who has decided this is the year they deal with the openings, and who then spends months researching.
That research is what the rest of this page is about, because it is entirely predictable and almost entirely unanswered.
02 / 06
The Insurance Question Is the One That Closes the Sale
Florida requires insurers to provide actuarially reasonable discounts, credits or other rate differentials, or reductions in deductibles, for fixtures and construction techniques that reduce wind loss, and the statute expressly names opening protection and window, door and skylight strength (Florida Statutes section 627.0629, 2025). That is the homeowner’s real question and it has a statutory answer.
Ask any installer what the customer actually asks and the answer is some version of: will this bring my insurance down.
The statute is directly on point. Florida provides that insurers must offer actuarially reasonable discounts, credits, or other rate differentials, or appropriate reductions in deductibles, for properties on which fixtures or construction techniques that reduce wind loss have been installed, and it names the categories: wind uplift prevention, roof strength, roof covering performance, roof-to-wall strength, wall-to-floor-to-foundation strength, opening protection, and window, door and skylight strength (Florida Statutes section 627.0629, 2025). It further provides that credits, discounts or other rate differentials for fixtures and construction techniques meeting the minimum requirements of the Florida Building Code must be included in the rate filing (Florida Statutes section 627.0629, 2025).
Opening protection and window strength are two of the seven named categories. That is not a marketing claim, it is the mitigation framework the statute describes, and an installer can explain it accurately without promising anybody a number.
Which is the crucial discipline here. Do not tell a homeowner what their discount will be. It depends on the property, the insurer, the inspection and the filing, and an installer who quotes a percentage is making a promise they do not control. Explain what the statute requires insurers to do, explain that the mitigation inspection is how the features get recognized, and tell them to take the specifics to their own carrier or agent.
A page that does that honestly is more persuasive than one that shouts about savings, because the homeowner has already read four pages that shouted and none that explained. It is also the page that gets shown when somebody asks an answer engine whether impact windows lower insurance in Florida.
03 / 06
Publish the Product Approval Numbers Nobody Else Publishes
Florida runs a statewide product approval database, managed by the Department of Business and Professional Regulation, where products carry FL numbers and can be searched by number, manufacturer or product type against a code version (Florida Building Commission, 2026). Publishing the numbers for what you install turns a sales claim into a public record the buyer can check.
This is the cheapest credibility available in the category and practically nobody takes it.
Florida operates a product approval system in which building products are assigned state approval numbers, commonly called FL numbers, and the public database can be searched by FL number, by manufacturer, or by product and application type against a given code version, with the 2023 Florida Building Code effective from December 31, 2023 (Florida Building Commission, 2026).
So the products you install already have public identifiers attached to public records. Most installer websites mention brand names and say the products are code approved. Very few list the actual approval numbers for the specific series they fit, and none of the national content farms can, because they do not install anything.
The move is simple. On each product page, name the series you install and its approval number, and tell the reader they can look it up themselves. You have converted an assertion into something verifiable, which is exactly the difference between a page a cautious buyer trusts and a page they discount.
It also has an effect beyond the buyer. Answer engines are trying to work out which pages describe real, accountable, identifiable businesses, and checkable identifiers are the strongest available evidence. That is the same argument we make about the disclosures Florida already requires on your advertising in what Florida requires your website to say, applied here to the product rather than the license.
One caution. Approvals are tied to code versions and products change, so a number published once and never revisited becomes wrong. Put a date on it and review it when the code version moves. And confirm the applicable requirements for a given address with the county, because this page describes a public database rather than giving code advice.
04 / 06
The Emergency Job and the Planned Project Are Different Businesses
Boarding up before a storm and replacing every opening in a house are different searches, different urgency and different money. Trying to serve both from one page produces a page that reads as urgent to the researcher and slow to the person in a hurry.
This trade has the sharpest version of a split that runs through most of home services.
One customer has a named storm in the forecast and needs something on the openings this week. They search in a hurry, from a phone, and they choose on availability and proximity. That search is settled in the map results and the phone call, and long-form content plays almost no part in it.
The other customer is replacing every window in a 1990s house, has been thinking about it since last season, will get three quotes, will ask about financing, and will read a great deal before contacting anybody. That search is settled by the research, over months.
The mistake is a single page trying to hold both. It ends up hedging: urgent enough to unsettle the researcher, slow and considered enough to lose the person with a storm coming. Split them. Give the emergency work a page written for speed, with service areas and response expectations stated plainly, and give the planned replacement a thorough page carrying the code, insurance and product questions above.
The same logic separates shutters from impact glass, which are different products with different price points and, for many buyers, a genuine decision between them. A page comparing them honestly, including where shutters are the better answer, will outperform two pages each insisting its own product wins. Buyers can tell when they are being sold rather than advised, and the trade has enough of the former already.
05 / 06
Why the National Content Cannot Answer Any of This
Every question above turns on Florida-specific material: a Florida statute, a Florida product approval database, a Florida code version and a hurricane season that only matters on this coast. A local installer holds all of it and mostly does not publish it.
It is worth being explicit about where the advantage sits, because local businesses routinely give it away.
The insurance answer is a Florida statute. The product verification runs through a Florida database with Florida approval numbers tied to a Florida code version. The seasonality is a Gulf and Atlantic phenomenon. None of it can be written by a national content operation, and none of it can be produced by a general purpose model with no access to the specific series you fit or the county you pull permits in.
Add to that the things only you know. Which window series actually holds up on a west-facing wall three blocks from the Gulf. What a 1980s Naples ranch usually needs before new units go in. How long permitting realistically takes in your county in September as opposed to March. Which lanai and slider configurations cause the surprises.
That material is the moat. It is specific, it is checkable, it is useful, and it is invisible to competitors who are not doing the work. It is also, not coincidentally, exactly what both a careful buyer and an answer engine are trying to find.
The reason most installers do not publish it is not secrecy. It is that it does not feel like marketing. It feels like the ordinary content of the job, which is precisely why it is worth so much on a page.
06 / 06
What to Publish, and in What Order
Build the planned-replacement page first, then the insurance explainer, then the product approval detail, then the emergency page and the shutters comparison. Keep the map results on a separate track, because that is what decides the urgent job.
A short order of work, arranged by what pays rather than what is easy.
First, the planned replacement page. Process, timeline, what is included, what changes the price, permitting, and an honest range. This is the page the four-month researcher is looking for and it barely exists in most markets.
Second, the insurance explainer, written the careful way described above: what the statute requires of insurers, how mitigation features get recognized, and a clear instruction to confirm specifics with their own carrier. No promised percentages.
Third, product detail with approval numbers and a date on them, so a buyer can verify what you install rather than taking your word for it.
Fourth, the emergency page, deliberately short and fast, and the shutters versus impact glass comparison written to advise rather than to sell.
Alongside all of it, treat the map results as a separate track that moves on different inputs. Categories, service areas, photographs of real completed installs and a steady flow of reviews decide who gets the urgent call, and no amount of writing substitutes for them.
One closing caveat that belongs on every page you build from this. Nothing here is code, legal or insurance advice. It describes published requirements and public records, and the county, the product approval database and your own carrier are the authorities on how any of it applies to a specific house.
If you would rather see what your site currently answers and where you stand against the other installers in your market, our free audit measures it and costs nothing, and the ongoing work is described on our construction SEO page.
Watch it work
Turn on what makes AI recommend you.
AI recommends the businesses it can read, trust and quote. Flip on the four signals we engineer, and watch your visibility climb and the answer rewrite itself.
THE FOUR SIGNALS WE ENGINEER
Illustrative · the four signals are the real system we build
Questions
This article, answered.
Jamie Kloncz · SEO Elite Agency, Naples
Florida requires insurers to provide actuarially reasonable discounts, credits or other rate differentials, or appropriate reductions in deductibles, for fixtures and construction techniques that reduce wind loss, and the statute expressly names opening protection and window, door and skylight strength among the categories (Florida Statutes section 627.0629, 2025). What that means for a particular property depends on the home, the insurer, the mitigation inspection and the rate filing, so treat any specific percentage you are quoted by a salesperson with caution and confirm with your own carrier or agent.
Jamie Kloncz · SEO Elite Agency, Naples
Florida runs a statewide product approval database in which products carry FL approval numbers and can be searched by number, by manufacturer, or by product and application type against a code version, with the 2023 Florida Building Code effective December 31, 2023 (Florida Building Commission, 2026). Ask your installer for the approval number of the exact series being quoted and look it up. An installer who publishes those numbers on the website has made that easy on purpose.
Jamie Kloncz · SEO Elite Agency, Naples
Months before the season, not during it. NOAA gives the Atlantic hurricane season as June 1 to November 30 with the peak on September 10 and most activity between mid-August and mid-October (NOAA National Hurricane Center, 2026). A page published during the peak has not had time to be crawled, trusted and ranked before the demand arrives, so the pages that capture a September buyer are the ones that went up in the spring and stayed live.
Jamie Kloncz · SEO Elite Agency, Naples
No. They are different customers with different urgency, different budgets and different decision processes. The emergency buyer chooses on availability and proximity within hours and is largely won in the map results. The replacement buyer researches for months and is won by thorough content. One page trying to serve both reads as too urgent for the researcher and too slow for the person with a storm coming.
Jamie Kloncz · SEO Elite Agency, Naples
Usually yes. Buyers comparing the two are high intent, and a genuinely balanced comparison, including the cases where shutters are the better answer for a given budget or opening, earns more trust than a page insisting one product always wins. Readers detect selling, and the honest comparison tends to be the page they return to when they are ready to buy.
Sources
- 1Florida Statutes section 627.0629 (Residential property insurance; rate filings), 2025 edition, read September 1, 2026 - insurers must provide actuarially reasonable discounts, credits, or other rate differentials, or appropriate reductions in deductibles, for properties on which fixtures or construction techniques demonstrated to reduce the amount of loss in a windstorm have been installed, including but not limited to fixtures or construction techniques that enhance wind uplift prevention, roof strength, roof covering performance, roof-to-wall strength, wall-to-floor-to-foundation strength, opening protection, and window, door and skylight strength; credits, discounts or other rate differentials for fixtures and construction techniques meeting the minimum requirements of the Florida Building Code must be included in the rate filing
- 2Florida Building Commission product approval database (floridabuilding.org, administered by the Department of Business and Professional Regulation), read September 1, 2026 - building products are assigned state approval numbers known as FL numbers and the public database is searchable by FL number, by manufacturer, or by product and application type against a selected code version, with the 2023 Florida Building Code effective December 31, 2023 and earlier code versions from 2001 onward remaining searchable
- 3NOAA National Hurricane Center, tropical cyclone climatology, read September 1, 2026 - the Atlantic hurricane season runs from June 1 to November 30, the peak of the season is September 10, and most activity occurs between mid-August and mid-October
Written by
SEO Elite Agency, Naples FL. Published .
Check this page has not changed
Every article is hashed when the site is built. This recomputes the hash of its text in your browser and compares it with the published record.
Related services